Two drivers can insure similar cars with the same company and still pay different amounts for their coverage simply because they choose different deductibles. One might prefer a lower deductible and a higher insurance premium, while the other accepts a larger potential repair bill in exchange for cheaper insurance.
Neither option is automatically better. The real question is whether the money saved on your premium is worth the additional amount you would have to pay if your car were damaged.
Understanding this trade-off can help you avoid a common mistake when shopping for car insurance: choosing the cheapest policy without considering what happens when you actually need to use it.
A deductible affects how much you pay toward certain covered claims, while your premium determines how much you pay to maintain your insurance policy. Although these two amounts are connected, they serve different purposes.
This guide explains how car insurance deductibles work, why changing yours can affect your premium, how to calculate whether a higher deductible is worthwhile, and what to consider before making a decision.
What Is a Car Insurance Deductible?
A car insurance deductible is the amount you must pay toward an eligible covered loss before your insurance company pays its share, subject to the policy’s terms and coverage limits.
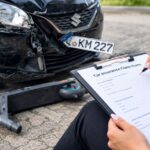
For example, suppose your car sustains $3,000 worth of covered damage in an accident and your collision deductible is $500. You would generally pay the first $500, while your insurer could cover the remaining $2,500 if the entire repair cost is approved.
The deductible is not a monthly payment. It becomes relevant when you make a claim under coverage that requires one.
Common deductible options include $250, $500, $1,000, and $2,000, although the amounts available depend on your insurer and policy.
A lower deductible usually means a higher premium, while a higher deductible generally reduces the premium in exchange for greater financial responsibility when a covered incident occurs.
What Is the Difference Between a Deductible and a Premium?
Your premium is the amount you pay to maintain your insurance policy. Depending on your insurer, you may pay monthly, every six months, or annually.
Your deductible is the amount you contribute toward a covered claim when the applicable coverage requires it.
Consider a driver paying $1,800 annually for car insurance with a $500 collision deductible. The driver pays the premium to keep the policy active, even if no accident occurs.
If an eligible collision claim arises, the driver may also have to contribute $500 toward the covered damage.
Paying your premium does not eliminate your responsibility for a deductible. Similarly, choosing a $1,000 deductible does not mean you must pay $1,000 every month. Knowing the difference makes it easier to compare insurance quotes and understand the actual costs of maintaining coverage.
How Does a Car Insurance Deductible Affect Your Premium?
Insurance companies consider several factors when calculating premiums, including your driving history, location, vehicle, coverage limits, and expected claims costs. Your deductible also matters because it determines how much of certain covered losses you agree to pay yourself.
When you choose a higher deductible, the insurer generally faces less financial responsibility for an eligible claim. This can result in a lower premium.
A lower deductible shifts more of the potential claim cost to the insurer, which generally means you pay more for the relevant coverage. Consider these hypothetical annual quotes:
| Deductible | Annual Premium |
|---|---|
| $250 | $1,950 |
| $500 | $1,800 |
| $1,000 | $1,620 |
| $2,000 | $1,470 |
These figures are illustrative rather than actual market rates. Your quotes may differ depending on your insurer, location, vehicle, and personal circumstances.
Notice that the premium decreases as the deductible increases. However, doubling your deductible will not necessarily cut your premium in half. The savings depend on the insurer’s pricing, so request quotes for different deductible amounts before making a decision.
Why Do Insurance Companies Offer Lower Premiums for Higher Deductibles?
A higher deductible reduces the amount an insurer may need to pay toward certain claims. It can also make drivers less likely to file small claims when the potential insurance payment is minimal.
For example, if your deductible is $1,000 and your covered repair costs $1,150, the potential insurance payment would be only $150, assuming the entire repair is covered. You might decide to pay for the repair yourself rather than submit a claim.
However, the premium savings should be weighed against the additional expenses you could face after a major accident.
Which Types of Car Insurance Have Deductibles?
Deductibles do not necessarily apply to every part of an auto insurance policy. Two common examples are collision and comprehensive coverage.
Collision Coverage
Collision coverage generally helps pay to repair or replace your insured vehicle after a covered accident involving another vehicle or an object, such as a fence or wall.
Suppose you accidentally hit a gate and your vehicle sustains $4,200 in covered damage. With a $500 collision deductible, your insurer could pay $3,700, leaving you responsible for $500. If your deductible were $1,500, your contribution would increase accordingly.
Collision coverage is particularly useful when repairing your vehicle without insurance would create a significant financial burden. Lenders and leasing companies may also require this coverage for financed or leased vehicles.
Comprehensive Coverage
Comprehensive coverage generally protects against covered damage or loss that does not result from a collision. Depending on your policy, this may include theft, vandalism, fire, hail, falling objects, and certain animal-related incidents.
Suppose a storm causes $2,400 in covered damage to your parked car. With a $500 comprehensive deductible, your insurer could pay $1,900.
Some insurers allow you to select different deductibles for comprehensive and collision coverage. You might choose a lower comprehensive deductible if you want to reduce your potential expenses following theft or weather damage.
Always check your policy because coverage terms and available options vary.
How to Decide Whether a Higher Deductible Is Worth It
The most useful way to compare deductibles is to calculate how much you would save annually and how much additional money you might need after a claim.
Step 1: Calculate Your Annual Savings
Suppose your insurer offers two options:
- A $500 deductible with an annual premium of $1,800.
- A $1,000 deductible with an annual premium of $1,650.
Choosing the higher deductible saves you $150 annually, if the difference remains unchanged, you would save $450 over three years and $750 over five years.
However, your premium could change at renewal, so these figures are only estimates based on the original quotes.
Step 2: Calculate the Break-Even Period
The difference between the two deductibles is $500. By choosing the higher option, you accept an additional $500 in potential out-of-pocket costs when a covered claim makes the full difference relevant. You can calculate how long it would take for your premium savings to equal that amount:
Break-even period = Additional deductible cost ÷ Annual premium savings
In this example:
$500 ÷ $150 = approximately 3.33 years.
It would take about three years and four months for the accumulated premium savings to equal $500, assuming the savings remain constant.
This calculation does not predict whether you will have an accident. It simply helps you compare the financial trade-off.
Step 3: Consider Your Emergency Savings
Even if a higher deductible looks attractive on paper, ask yourself whether you could afford to pay it immediately.
For example, choosing a $1,000 deductible may reduce your premium, but it could become a problem if you have only $300 in accessible savings. An unexpected repair bill could force you to borrow money or delay essential expenses.
If you have enough savings to handle a larger deductible comfortably, accepting more financial responsibility may make sense. Choose an amount you could realistically pay without disrupting your essential bills.
What Happens If Repairs Cost Less Than Your Deductible?
If the cost of a repair is lower than your applicable deductible, your insurance will generally pay nothing toward that repair. Suppose your collision deductible is $1,000, but repairing a damaged bumper costs $850.
You would normally pay the full $850 yourself because the repair cost falls below your deductible. If the repair costs $1,150, the potential insurance payment would be only $150, assuming the entire repair is covered.
For minor damage, compare the cost of paying for repairs yourself with the potential benefit of submitting a claim.
Remember that the effect of a claim on your future premium depends on factors such as fault, claim type, state regulations, and your insurer’s rating practices. A premium increase is not automatic in every situation.
Does Your Deductible Affect a Total-Loss Settlement?
Yes, when a covered accident results in a total loss, the insurer generally calculates the vehicle’s value under the policy and subtracts the applicable deductible where required.
Suppose your insurer determines that your totaled vehicle has an actual cash value of $18,000 and your collision deductible is $1,000.
The simplified settlement calculation would be:
- Vehicle value: $18,000.
- Deductible: $1,000.
- Potential settlement: $17,000.
Other policy terms and adjustments may affect the final amount.
The difference can be particularly important if you still owe money on a vehicle loan. If your outstanding loan balance is $19,500, a $17,000 settlement would leave a $2,500 shortfall.
You would generally remain responsible for that difference unless applicable gap insurance or another arrangement covers it.
This is one reason to consider your vehicle’s value and outstanding loan balance when reviewing your insurance coverage.
Do You Pay a Deductible When Another Driver Causes the Accident?
Not necessarily, if another driver causes an accident, you may file a claim with their insurer or use your own collision coverage, depending on the circumstances.
If you use your collision coverage, your deductible may apply initially. Your insurer may later recover the payment from the other driver’s insurer and reimburse some or all of your deductible, depending on the outcome.
If the other driver’s insurer accepts liability and pays your claim directly, your own collision deductible may not apply.
The result depends on the circumstances, available evidence, state laws, and insurance policy terms. Ask your insurer how deductible reimbursement works before assuming you will automatically receive your money back.
Conclusion
A car insurance deductible determines how much you contribute toward certain covered losses, while your premium is the amount you pay to maintain your policy.
Choosing a higher deductible can reduce your insurance costs, but it also means accepting greater financial responsibility when damage occurs. A lower deductible generally costs more upfront through your premium but can make unexpected repairs easier to manage.
Before deciding, compare quotes, calculate the annual savings, and consider how much money you could access quickly if you needed to make a claim.
The best deductible is not necessarily the highest or lowest available. It is the one that balances affordable premiums with out-of-pocket costs you can comfortably manage.
Frequently Asked Questions
Can I Change My Deductible Later?
Many insurers allow deductible changes when purchasing coverage, updating a policy, or renewing it. Some permit changes during the policy term. Check with your insurer to confirm availability, the new premium, and when the change becomes effective. A change generally will not apply retroactively to damage that has already occurred.
Can Collision and Comprehensive Coverage Have Different Deductibles?
Yes, many insurers allow separate deductibles for these coverages. Available choices and pricing vary, so compare both before selecting your policy.